
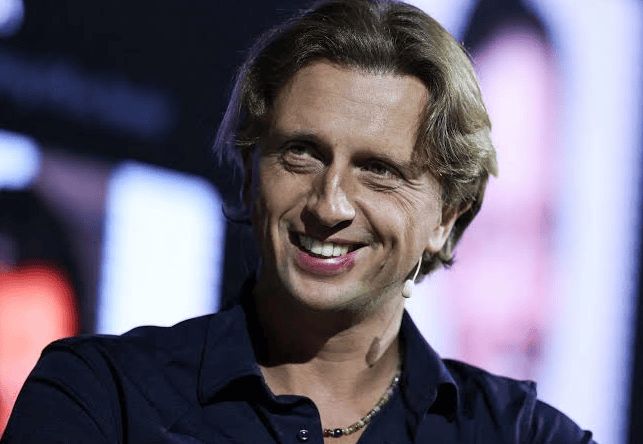
Some entrepreneurs build companies. Others attempt to redesign entire industries.
Nik Storonsky belongs to the second category.
In 2015, the former derivatives trader co-founded Revolut with a relatively simple idea: make spending and transferring money internationally easier, faster and less expensive. More than a decade later, that idea has evolved into something considerably more ambitious.
Revolut now serves more than 80 million customers across 40 countries, while its founder is pursuing a much bigger objective: transforming the fintech company into a truly global bank.
For September 2026, Camel Move Magazine’s Entrepreneur of the Month is Nik Storonsky, a founder whose story illustrates how technology, financial expertise and an uncompromising approach to growth can challenge one of the world’s oldest industries.
Before Revolut: Learning Finance From the Inside
Storonsky did not enter entrepreneurship from outside the financial system.
Before founding Revolut, he worked as an emerging-markets equity derivatives trader at Lehman Brothers and Credit Suisse. According to Revolut, he traded more than $2 billion across options, swaps and foreign-exchange instruments.
That background became important to the company he would eventually create.
Working inside traditional financial institutions gave Storonsky first-hand experience of how money moved across borders and where customers encountered friction.
Rather than simply accepting those systems as fixed, he began looking for ways technology could make them simpler.
His academic background was equally unconventional for a future fintech founder. Storonsky holds a master’s degree in applied physics and mathematics from the Moscow Institute of Physics and Technology and a master’s degree in economics from the New Economic School in Moscow.
The combination of quantitative training and financial experience would become part of his entrepreneurial toolkit.
The Idea Behind Revolut
When Revolut launched in 2015, international financial transactions remained heavily dependent on traditional banks, exchange fees and complicated processes.
Storonsky’s proposition was straightforward: create a digital financial service that could make international money management feel more like using a modern technology product.
The initial business focused heavily on foreign exchange and international spending.
But the underlying ambition was larger.
Instead of building another financial product, Storonsky and co-founder Vlad Yatsenko began constructing an entire financial platform.
Yatsenko brought a software-engineering background to the company after working on financial systems at major investment banks including UBS and Deutsche Bank. Revolut’s own account of its founding describes how the two founders combined financial and technical expertise to build a new generation of digital banking.
That combination became one of Revolut’s defining characteristics.
Finance understood through technology.
Technology designed around financial behaviour.
From Startup to Global Platform
Revolut’s expansion was remarkably broad.
What began as a service aimed at making foreign currency transactions easier gradually developed into an ecosystem encompassing payments, cards, savings, investments, business services, credit and other financial products.
The company also expanded geographically at an aggressive pace.
By September 2026, Revolut says it serves more than 80 million customers worldwide.
The scale is significant because the company was not simply expanding as a conventional bank.
It was attempting to build financial infrastructure around a technology-first operating model.
That distinction has remained central to Storonsky’s vision.
The Entrepreneurial Philosophy
Storonsky’s leadership style has often been associated with speed, efficiency and a willingness to challenge established assumptions.
The September 2026 Financial Times profile of Revolut describes a company culture influenced by Silicon Valley technology businesses, with an emphasis on rapid execution and comparatively low bureaucracy.
The philosophy is visible in the company’s broader ambition.
Traditional banks often develop through generations of physical infrastructure, branch networks and established financial systems.
Revolut emerged in an environment where the smartphone could become the primary interface between a customer and their money.
That allowed the company to approach banking from a different starting point.
The question was no longer:
How can a bank make its existing services digital?
It became:
What would banking look like if it were designed as a technology product from the beginning?
That distinction helped define Revolut’s identity.
Building Beyond the Fintech Label
The word “fintech” once seemed to describe Revolut perfectly.
But Storonsky increasingly appears to be aiming beyond that category.
The company has been expanding into traditional banking activities, including lending and deposits, while pursuing banking licenses in major markets.
In the United States, Revolut submitted its application for a national banking charter in March 2026.
Then, on September 3, 2026, the U.S. Office of the Comptroller of the Currency granted Revolut conditional approval to form a national bank.
The company says it is continuing the remaining regulatory processes with the FDIC, Federal Reserve and OCC, with a proposed U.S. bank launch planned for 2027.
For Storonsky, this represents a significant step toward the company’s central ambition.
Revolut is no longer simply trying to be an alternative to banks.
It is attempting to become one.
The Global Bank Ambition
Storonsky’s stated vision is to create what Revolut describes as the world’s first truly global bank.
The September 2026 Financial Times profile places that ambition at the centre of the company’s next phase.
That objective comes with an enormous challenge.
Banking is one of the most heavily regulated industries in the world.
Operating across multiple countries means navigating different regulatory systems, consumer-protection requirements, financial rules and cultural expectations.
The more Revolut becomes a bank, the more its technology company must operate within the structures of traditional financial regulation.
This creates an interesting entrepreneurial paradox.
The company was created to challenge traditional banking.
Now, its next stage requires it to master the same regulatory environment that established banks have operated within for decades.
A Different Approach to Risk
Storonsky’s background in financial markets has also influenced his approach to risk.
In a September 2026 interview, he described his ambition for Revolut as a global consumer bank with effectively zero risk. The company currently maintains a relatively low loan-to-deposit ratio and has pursued a more cautious approach to holding loans on its balance sheet.
This matters because lending is one of the biggest differences between a fintech platform and a traditional bank.
Payments can be highly scalable.
Lending introduces credit risk.
The transition therefore represents more than simply adding another product.
It changes the economics and responsibilities of the business.
For an entrepreneur who originally built Revolut around making financial services simpler, this next stage requires balancing growth with the fundamental risks of banking.
The U.S. Opportunity
America represents one of the most important chapters in Revolut’s expansion.
The company has identified the United States as a major growth market, and its 2026 banking-charter application represented a significant step toward establishing a more complete banking operation there.
Conditional approval arrived in September, giving the company’s U.S. strategy another important milestone.
The significance extends beyond the American market itself.
Success in the United States could strengthen Revolut’s position as a global financial platform rather than a European fintech with international ambitions.
It would also place the company more directly alongside some of the world’s largest financial institutions.
The IPO Question
Another major chapter on Revolut’s horizon is a potential public listing.
In September 2026, Storonsky said the company is considering a dual listing in New York and London. Reuters reported that the founder confirmed the company was evaluating both markets, while a public offering is currently anticipated around 2028, subject to market conditions.
For a founder, an IPO can represent both an achievement and a new challenge.
Going public creates greater access to capital and liquidity, but it also introduces increased scrutiny from investors and the public markets.
For Storonsky, the question is not simply whether Revolut can become bigger.
It is whether the company can preserve the entrepreneurial speed that helped create it while becoming an increasingly complex financial institution.
A New Generation of Financial Entrepreneurship
Storonsky represents a broader change in entrepreneurship.
The traditional financial entrepreneur might have built a bank through capital, branches, relationships and decades of institutional experience.
The fintech entrepreneur begins somewhere else.
The starting point can be a smartphone, software engineers, a product team and a frustration with an existing customer experience.
Revolut’s story demonstrates how technology companies can enter industries once dominated almost exclusively by institutions.
But it also shows that disruption does not eliminate the fundamentals of business.
Scale still matters.
Trust still matters.
Regulation still matters.
Capital still matters.
And perhaps most importantly, customers still determine whether an idea becomes a business or remains simply an interesting piece of technology.
Beyond Banking
Storonsky’s entrepreneurial ambitions have also extended beyond Revolut.
The Financial Times reported in September 2026 that he has launched AI-focused venture capital funds and remains active in exploring opportunities outside traditional financial technology.
That interest reflects another characteristic of modern entrepreneurship: successful founders increasingly operate across multiple industries rather than remaining tied permanently to the company that made them famous.
For Storonsky, fintech may be the foundation.
AI, venture capital and other technology sectors could become part of the next chapter.
What Entrepreneurs Can Learn From Storonsky
The Revolut story offers several lessons for entrepreneurs.
Solve a frustration you understand
Storonsky had worked inside the financial system before attempting to change it.
His understanding of foreign exchange, payments and banking gave him a clear view of where consumers experienced friction.
Think beyond the first product
Revolut did not remain a foreign-exchange card.
It expanded into a broader financial ecosystem.
The original product became the entry point rather than the final destination.
Build for scale from the beginning
A global financial platform requires technology capable of serving customers across markets.
Revolut’s international ambition was embedded in the company’s model rather than added as an afterthought.
Challenge established assumptions
One of the defining characteristics of entrepreneurship is asking why an existing system works the way it does.
Storonsky’s career demonstrates the potential of questioning processes that customers have simply learned to tolerate.
Understand that growth changes the business
The most important entrepreneurial challenge may not be launching a company.
It may be adapting when the company becomes too large to operate like the startup that created it.
Revolut’s transition from fintech challenger to regulated global banking platform illustrates precisely that challenge.
The Road Ahead
Revolut now finds itself at an unusual point in its development.
The company has achieved the scale of a major financial institution while continuing to present itself as a technology-driven challenger.
It has more than 80 million customers, operates across dozens of countries, has secured major banking milestones and is exploring the possibility of eventually entering public markets.
But scale creates its own demands.
As Revolut expands into lending, banking and corporate financial services, the company must navigate the tension between speed and control, innovation and regulation, growth and risk.
There have also been recent challenges. In September 2026, reports emerged that the personal data of nearly 700 Revolut customers had been improperly disclosed to scammers, prompting regulatory scrutiny. Revolut said the incident did not compromise customer funds and that it had notified the relevant authorities.
Such episodes underline a central reality of Storonsky’s next chapter: building a global bank is fundamentally different from building a successful startup.
The expectations are higher.
The consequences are larger.
And the margin for error becomes smaller.
The Entrepreneur of September
Nik Storonsky’s entrepreneurial story is ultimately a story about scale.
He began with a problem he encountered personally in the financial system and turned it into a technology company.
That company became a fintech platform.
The platform is now attempting to become a global bank.
And the entrepreneur behind it continues to push into new areas of technology and investment.
Whether Revolut ultimately becomes the global banking institution Storonsky envisions will depend on factors ranging from regulation and competition to consumer trust and the company’s ability to maintain its distinctive technology-driven culture.
What is already clear is the scale of the experiment.
Storonsky is not simply building another financial app.
He is attempting to rethink what a bank can look like in a world where money, technology and everyday life are increasingly inseparable.
For Camel Move Magazine’s September 2026 Entrepreneur of the Month, Nik Storonsky represents the modern founder at his most ambitious: identifying a weakness in an established industry, building an alternative from the ground up, scaling it internationally, and then attempting to redefine the industry itself.
The next chapter is no longer about disrupting banking.
It is about building one.
Comments are closed.